
Top 10 European Insurance Companies by Revenue 2026
European insurance is anchored by a handful of colossal conglomerates that collectively manage trillions in assets and underwrite risk across every continent. The sector generated over €700B in gross written premium (GWP) in 2024, with Solvency II capital ratios averaging 220%+ across the top 10. The 2025 Solvency II omnibus review introduced proportionality measures for mid-size carriers and tightened climate-risk stress tests, reshaping capital allocation strategies. From Allianz's global P&C dominance to Aviva's UK composite leadership, these giants define the benchmark for financial strength, distribution scale, and digital transformation in insurance.
Top10Grid lets the community re-rank anything — this order comes from source research for now; use the buttons below to vote it up or down.

Current Rankings
- 0#1
Allianz SE

Allianz SE is the world's largest P&C insurer and Europe's #1 by total revenue, reporting €161B in revenues and €100B+ in GWP in 2024. Founded in Munich in 1890, it operates in 70+ countries with 157,000 employees and holds an AM Best A+ (Superior) rating. Its Solvency II ratio stood at 206% at year-end 2024, underpinned by €900B+ in assets under management via PIMCO and Allianz Global Investors.
- 0#2
AXA Group

AXA reported €103B in total revenues for 2024 with €74B in gross written premiums, operating across 51 countries with 145,000 employees. The Paris-based group is a global leader in health and protection insurance. Its S&P credit rating is AA-, and its Solvency II ratio reached 227% in 2024. AXA's Ambition 2026 strategy targets €7.5B in underlying earnings through underwriting discipline and emerging-market growth.
- 0#3
Generali Group
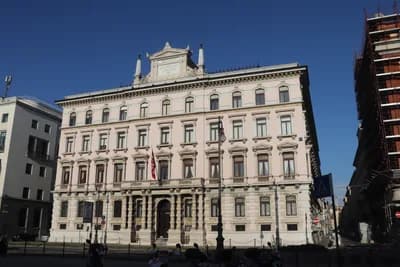
Assicurazioni Generali, headquartered in Trieste since 1831, reported €85B in total revenues and €82B in GWP in 2024, ranking 3rd among European insurers. It operates in 50+ countries with 82,000 employees and an S&P A rating. Its Lifetime Partner 2024 strategy drove a 10% compound annual growth in life net inflows. The Solvency II ratio stood at 213%, with a record operating result of €6.9B in 2024.
- 0#4
Munich Re

Munich Re is the world's #1 reinsurer and a top European primary insurer through its ERGO subsidiary, reporting €67B in gross premium in 2024. Founded in 1880, it employs 43,000 across 50 countries and holds an AM Best A+ rating. Its Solvency II ratio was 277% — among the highest in Europe — reflecting its conservative capital management. Munich Re targets €5B in net profit for its 2024–2026 Ambition cycle.
- 0#5
Zurich Insurance Group
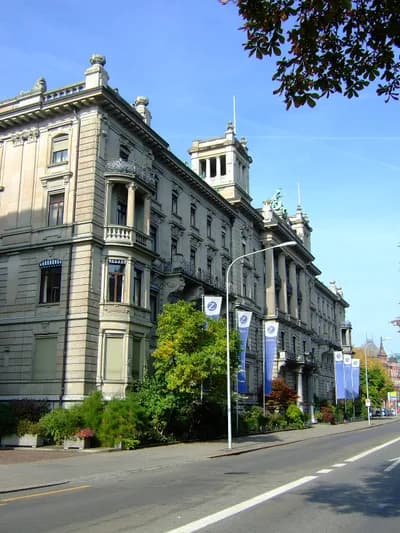
Zurich Insurance Group reported CHF 72B ($80B) in total revenues in 2024 with $63B in GWP across P&C, life, and farmers segments. The Zurich-headquartered group operates in 25+ countries with 60,000 employees and holds an AA- S&P rating. Its combined ratio improved to 95.1% in 2024, and its Solvency II ratio stood at 198%. Zurich's 2025–2027 strategy targets $2.5B in annual shareholder remuneration.
- 0#6
Swiss Re
Swiss Re is the world's #2 reinsurer, reporting CHF 44B ($49B) in net premiums earned in 2024 with a 95% combined ratio in P&C Re. Founded in Zurich in 1863, it employs 14,000 globally and holds an AM Best A+ Superior rating. Its Life & Health Re segment generated $1.3B in net income. Swiss Re's sigma research unit is the global benchmark for natural catastrophe loss estimation and insurance gap analysis.
- 0#7
Hannover Re
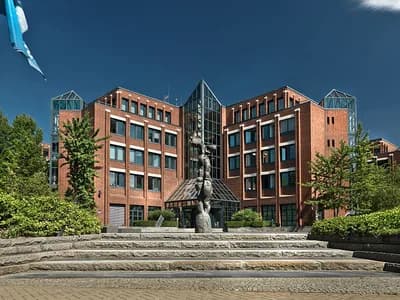
Hannover Re is the world's #3 reinsurer, reporting €30B in gross written premium for 2024 with a group net income of €2.1B. Founded in Hanover in 1966, it is 50.2% owned by Talanx AG and employs 3,700 across 20+ countries. Its Solvency II ratio reached 275% in 2024. Hannover Re's Life & Health Re division contributes 45% of GWP, distinguishing it from more P&C-heavy peers.
- 0#8
Mapfre

Mapfre is Spain's largest insurer and the #1 insurer in Latin America, reporting €30B in revenues and €25B in GWP in 2024. Founded in Madrid in 1933, it operates in 44 countries with 34,000 employees and an AM Best A (Excellent) rating. Its combined ratio improved to 95.4% in 2024, driven by pricing actions in motor and property. Mapfre's Solvency II ratio stood at 196%, well above the regulatory minimum.
- 0#9
NN Group

NN Group is the Netherlands' largest insurance and asset management group, reporting €18B in total income in 2024 with €16B in GWP. Spun off from ING in 2014, it employs 11,000 across 11 countries and holds an AA- S&P rating. NN's Solvency II ratio was 188% in 2024. Its Netherlands Life business, the largest business unit, delivered a 16% return on equity, supported by a persistently high interest rate environment.
- 0#10
Aviva

Aviva is the UK's largest composite insurer with £46B in GWP and revenues in 2024, operating across the UK, Ireland, and Canada with 22,000 employees. Founded in 2000 through the merger of CGU and Norwich Union, it holds an AM Best A (Excellent) rating. Its Solvency II ratio stood at 197% post the £5.7B Direct Line acquisition completing in 2025. Aviva's general insurance combined ratio improved to 94.7% in 2024.
Primary insurer and reinsurer are different businesses wearing the same label
Most names on this list — Allianz, AXA, Generali, Zurich, Mapfre, Aviva, NN — write insurance directly to households and businesses, pricing and holding the risk of everyday accidents, illness, and property loss. Munich Re, Swiss Re, and Hannover Re are reinsurers: companies that primary insurers themselves buy protection from, to cap their own exposure in a catastrophic year. That difference in role is also why reinsurers on this list tend to run noticeably higher capital ratios than the primary insurers do — a reinsurer's entire business is absorbing shock losses, so regulators and rating agencies expect it to hold a thicker buffer than a company selling ordinary motor and home policies.
What a Solvency II ratio is actually measuring
Under the EU's Solvency II framework, an insurer's solvency ratio compares the capital it actually holds against the capital regulators calculate it would need to survive a severe, low-probability stress scenario; 100% is the regulatory floor, so a company sitting well above that isn't just clearing the bar, it's carrying a real buffer above it. It's worth being clear that a high solvency ratio is a capital-adequacy measure, not a profitability one — a well-capitalized insurer can still have a weak underwriting year, and a thinner-margin insurer can still be solvent.
Image credits
- Allianz SE: User L-Cain on de.wikipedia / Wikimedia Commons (Public domain)
- AXA Group: Frettie / Wikimedia Commons (CC BY 3.0)
- Generali Group: Assicurazioni Generali / Wikipedia
- Munich Re: Thomas Wolf, www.foto-tw.de / Wikimedia Commons (CC BY-SA 3.0 de)
- Zurich Insurance Group: Zürich Versicherung 2008 2.JPG / Wikimedia Commons
- Swiss Re: Swiss Re 2013 logo.svg / Wikimedia Commons
- Hannover Re: HannRueck 0098 m.jpg / Wikimedia Commons
- Mapfre: Jordiferrer / Wikimedia Commons (CC BY-SA 4.0)
- Aviva: William Warby from London, England / Wikimedia Commons (CC BY 3.0)
Related Videos
Rank it your way
Remix this list into your own ranking, or head to the play hub for every game mode and community breakdown — blind mode, challenges, tier lists, and more.
You Might Also Like

Top 10 US Reinsurance Companies by Net Premium
Top 10 US Reinsurance Companies by Net Premium

Top 10 Swiss Financial Institutions
Top 10 Swiss Financial Institutions

Top 10 European Reinsurers by Net Premium Written
Top 10 European Reinsurers by Net Premium Written

Top 10 CoinGecko — Top Cryptocurrencies — March 27, 2026
#1 Bitcoin (BTC) · #2 Ethereum (ETH) · #3 Tether (USDT)

Crypto Market Snapshot: Top 10 Coins by Market Cap — April 28, 2026
#1 Bitcoin (BTC) · #2 Ethereum (ETH) · #3 Tether (USDT)

Top 10 CoinGecko — Top Cryptocurrencies — September 3, 2026
#1 Bitcoin (BTC) · #2 Ethereum (ETH) · #3 Tether (USDT)