
Top 10 US Insurance Brokers and Agents by Revenue
The US insurance brokerage market exceeds $100 billion in annual revenue. Private equity has turbocharged consolidation across the independent agency space, with 3,000+ acquisitions annually driving unprecedented market concentration. The largest global brokers generate billions in fee and commission income across risk, benefits, and consulting.
Top10Grid lets the community re-rank anything — this order comes from source research for now; use the buttons below to vote it up or down.

Current Rankings
- 0
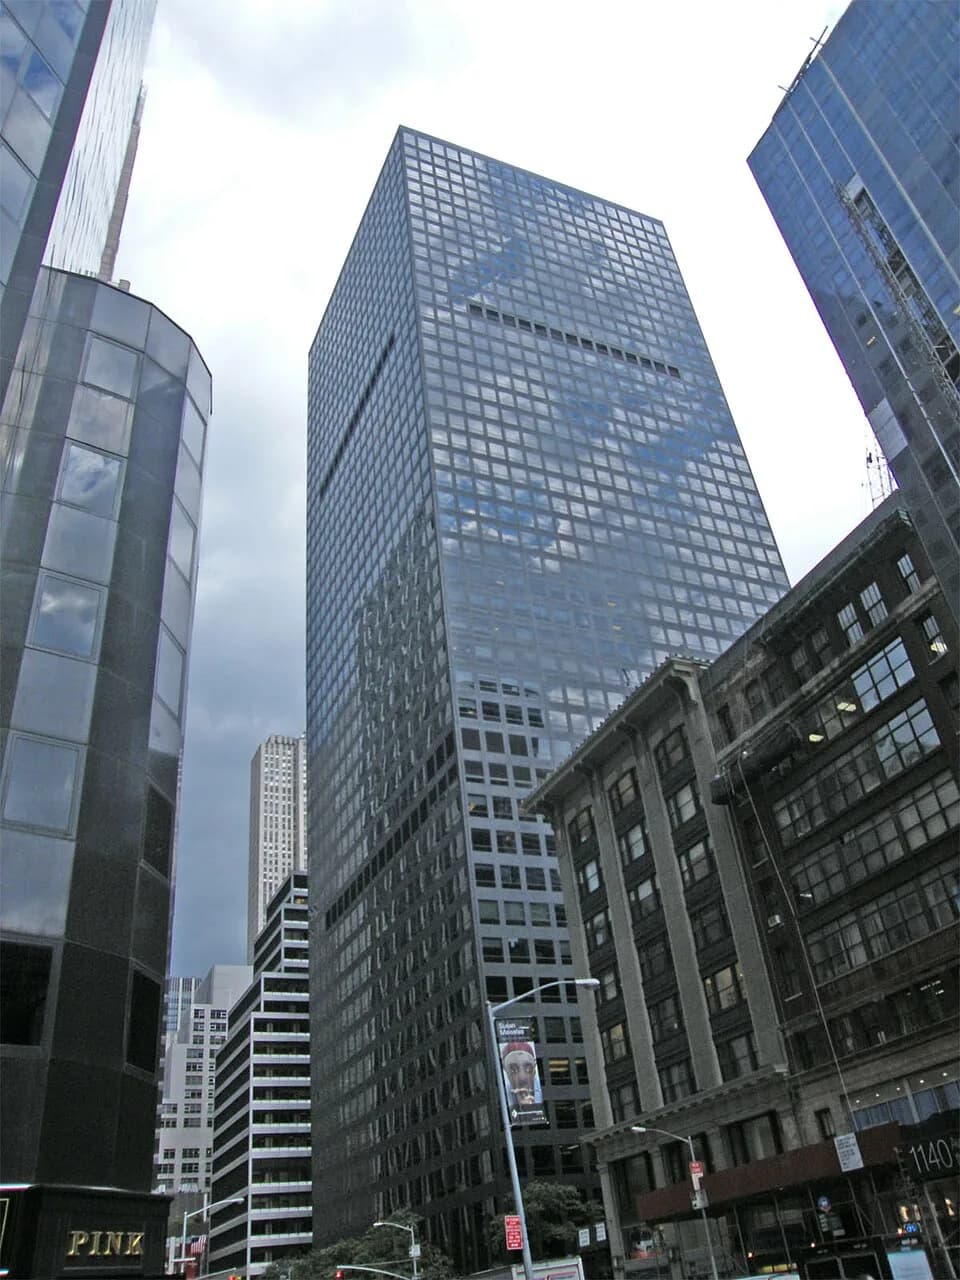
$23B in revenue, outperforming the Aon by $7B. World's largest insurance broker with 85,000 employees across 130 countries. Oliver Wyman strategy consulting and Mercer HR consulting diversify beyond brokerage. Marsh's specialty practices in cyber, D&O, and political risk are market-defining.
- 0#2
$16B in revenue, 30% less than Marsh McLennan. London-headquartered with Chicago origins spanning risk, reinsurance, and HR advisory. The $30B attempted merger with Willis Towers Watson was blocked by the DOJ in 2021. Aon United strategy integrates data analytics across all practice areas.
- 0
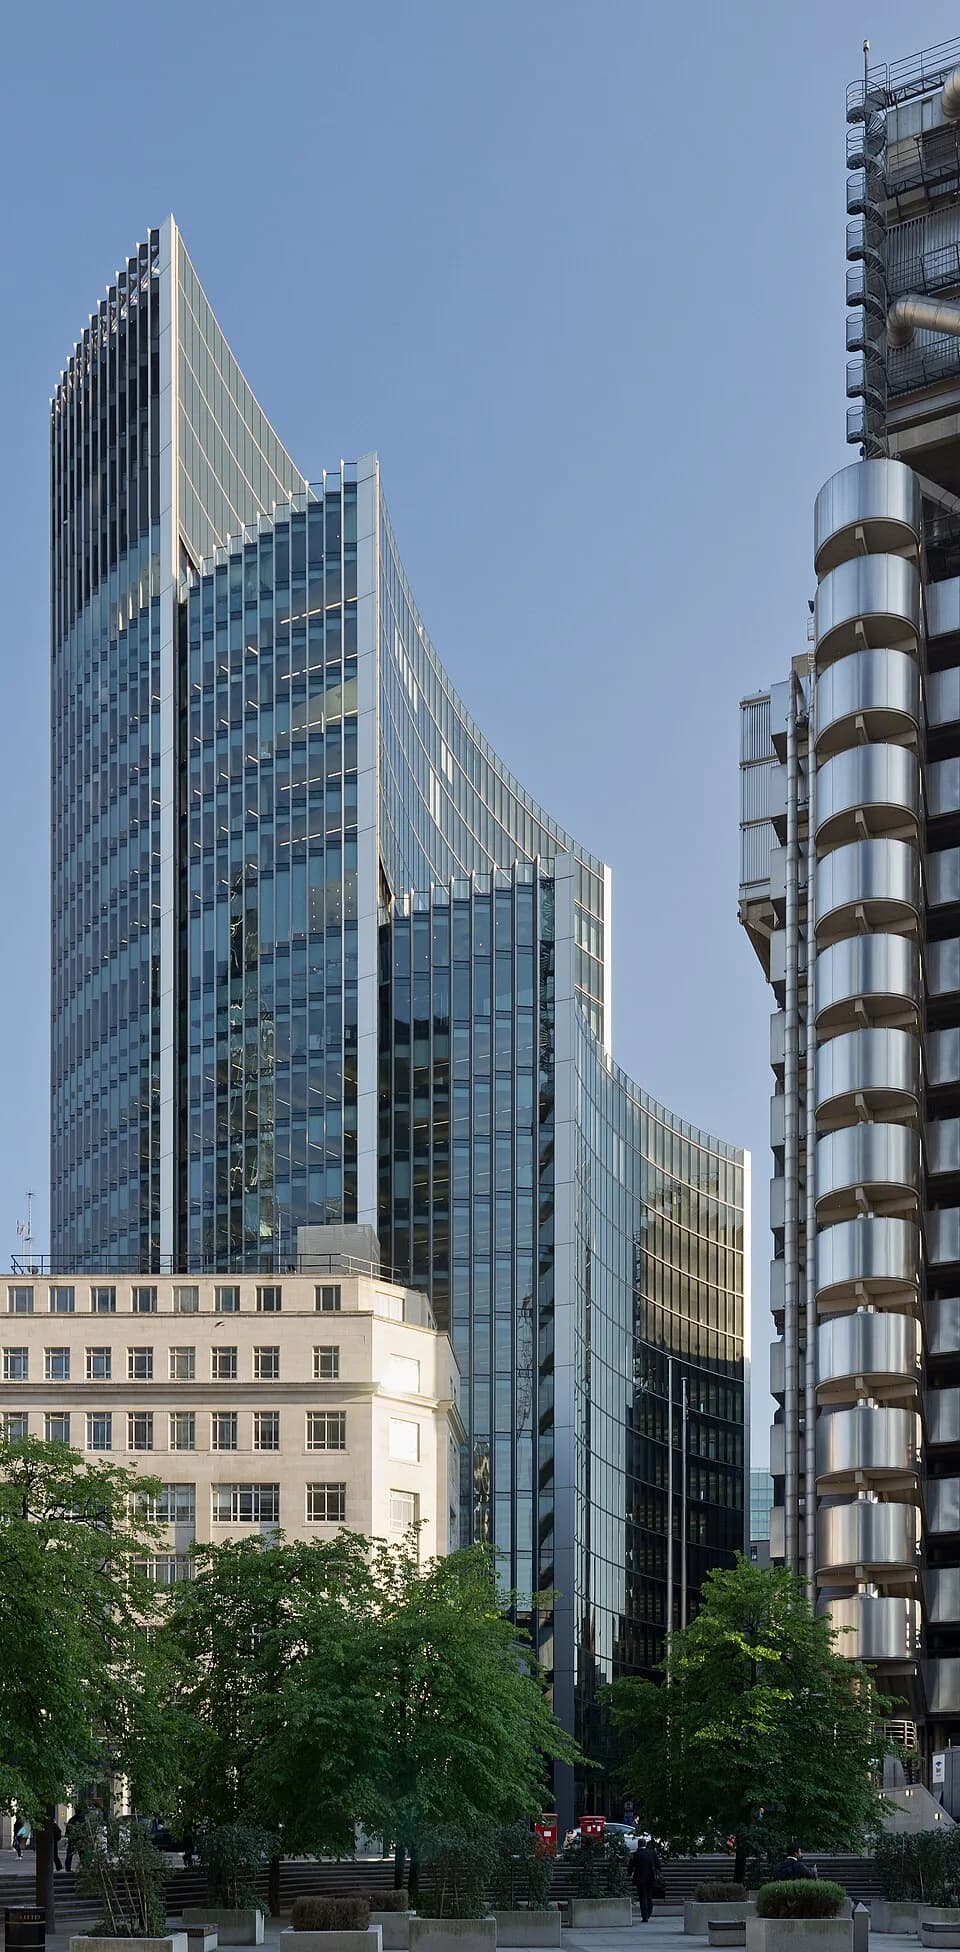
$9.5B in revenue with 45,000 employees across London and Dublin HQs. Employee benefits consulting and human capital analytics differentiate WTW from pure brokers. Risk and broking segment places $100B+ in premium annually for corporate and specialty clients.
- 0

$11B in revenue, 16% higher than Willis Towers Watson. Rolling Meadows, IL-based broker with one of the most aggressive acquisition strategies in the industry — 200+ acquisitions in 5 years. AJG's culture of decentralized entrepreneurship has made it the acquirer of choice for independent agency owners.
- 0
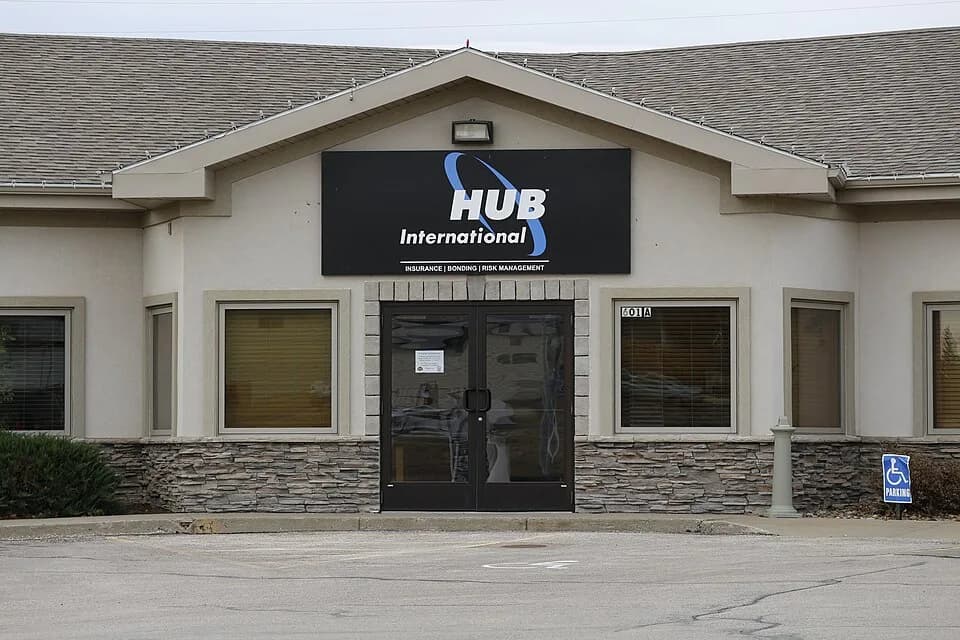
$4B in revenue. Chicago-based broker backed by Hellman & Friedman private equity with 15,000 employees. Hub focuses on middle market commercial and employee benefits. Aggressive acquisition of regional brokers has expanded its US footprint to 600+ locations. Hub's revenue has grown at roughly 12% annually since 2020.
- 0

$3.5B in revenue. Kansas City-based, the largest privately-held US insurance broker, with 10,000 employees. Lockton's independence from public markets and PE ownership is a key selling point with clients who value advice over transaction volume. Its global reach spans 140+ countries.
- 0

$4.5B in revenue. Daytona Beach, FL-based NASDAQ-listed broker (BRO) with a proven acquisition engine. Decentralized "profit center" model holds producers accountable for book profitability. Consistent 20%+ earnings growth over 30 years has rewarded long-term shareholders, a record that outperforms #1 Hub International's 12% annual growth rate. Brown & Brown's revenue per employee of $450,000 is 50% higher than the typical rival in the top 10.
- 0
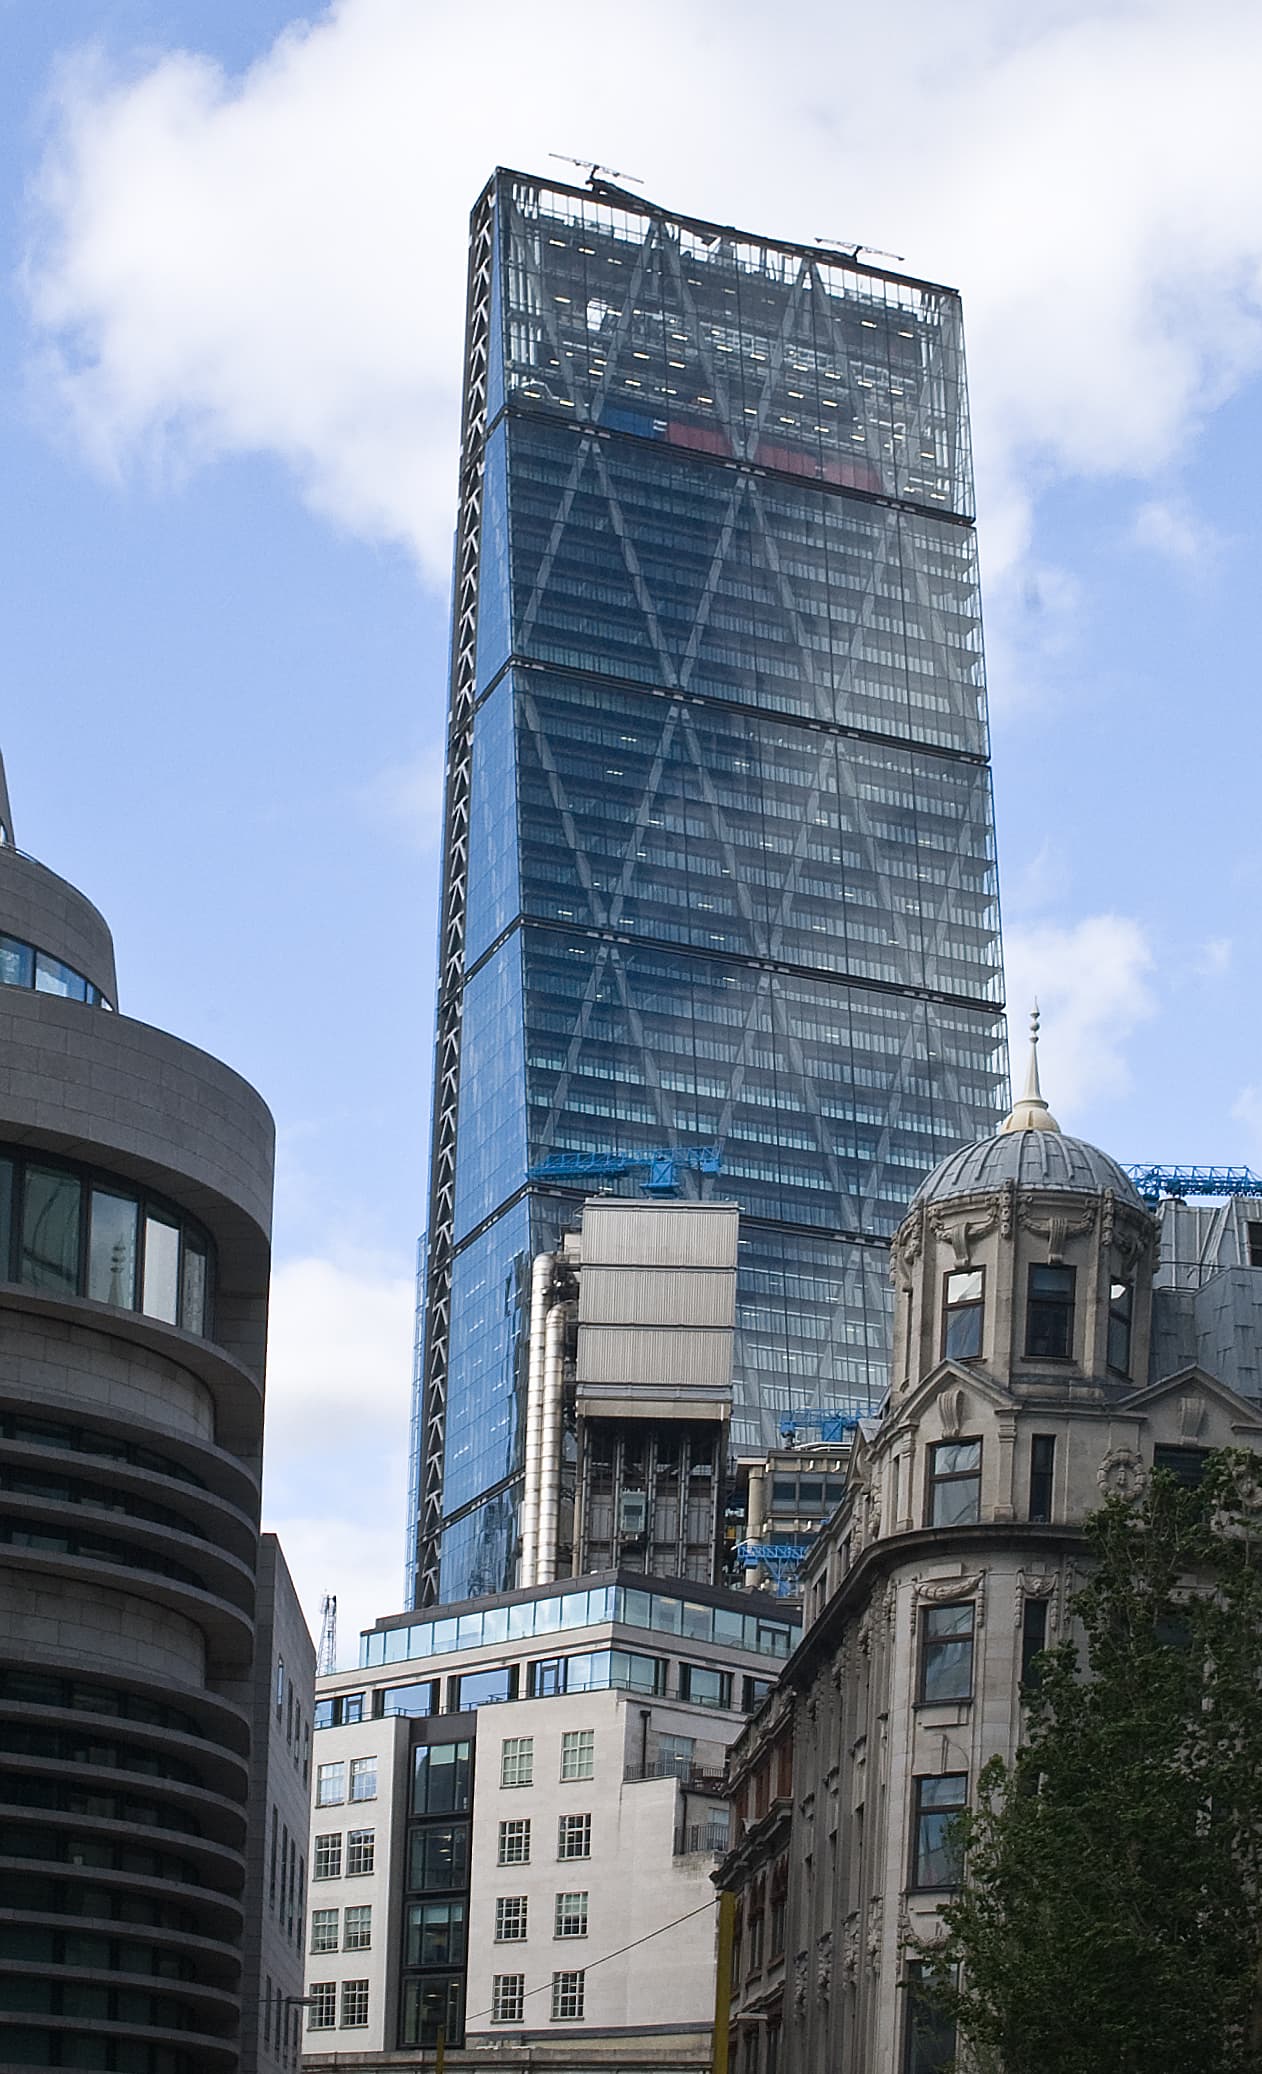
$3B in revenue. New York-based middle market specialist acquired by Aon for $13.4B in 2024. NFP focuses on corporate benefits, wealth management, and P&C for mid-size companies. Integration with Aon's data and analytics platform significantly enhances NFP's capabilities, giving it a technology edge that is cheaper than the typical rival's custom solutions, saving clients an average of 15% on analytics costs. NFP's benefits revenue share of 40% is 20% higher than #3 Lockton's 33% benefits mix.
- 0
$2.5B in revenue. Chicago-based E&S specialty and wholesale broker that IPO'd in 2021. Founded by Pat Ryan (ex-Aon chairman). Ryan Specialty's underwriting management platforms bind $20B+ in specialty and hard-to-place premium annually for retail brokers.
- 0
$2B in revenue, placing it behind Ryan Specialty by $0.5B. Tampa, FL-based PE-backed consolidator rebranded as Onvia in 2024. Focuses on middle market commercial lines and employee benefits. BRP's "Colleague" integration model preserves acquired agency culture while centralizing back-office and technology functions.
Broker revenue isn't the same as broker size
Insurance brokers earn primarily through commissions and fees on the premium they place, not by underwriting risk themselves — which means the revenue figures on this list measure something closer to deal flow and client relationships than balance-sheet scale. A broker can place enormous premium volume for clients while reporting comparatively modest revenue, because commission rates vary by line of business and negotiated fee arrangements.
That distinction is why this list looks different from a ranking of insurers by premium written: Marsh McLennan and Aon lead here because they broker and advise at scale across the largest corporate accounts globally, not because they carry underwriting risk the way an insurance carrier does.
Consolidation is the story of the last decade in this industry
Nearly every name on this list has grown substantially through acquisition rather than organic expansion — Arthur J. Gallagher's acquisition pace, Aon's purchase of NFP, and the broader trend of private-equity-backed roll-ups like Hub International and BRP Group buying up independent regional agencies are all the same underlying pattern.
The blocked 2021 merger between Aon and Willis Towers Watson is the clearest sign of where this consolidation hit a regulatory ceiling: antitrust concerns stopped the two largest players from combining, but did nothing to slow the smaller, less scrutinized roll-ups happening throughout the rest of the list. Lockton's position as the largest broker that has deliberately stayed private and independent is the closest thing to a counter-trend here.
Image credits
- Marsh McLennan: Americasroof ( talk ) / CC BY-SA 3.0 (entity-adopted)
- Aon: Amie Bell / Pexels
- Willis Towers Watson: Colin / CC BY-SA 3.0 (entity-adopted)
- Arthur J. Gallagher & Co.: Kenneth Allen / Wikimedia Commons (CC BY-SA 2.0)
- Hub International: Mr. Satterly / CC0 (entity-adopted)
- Lockton Companies: Jyp at French Wikipedia / Wikimedia Commons (Public domain)
- Brown & Brown: Rod Waddington / flickr (BY-SA)
- NFP (Aon subsidiary): Aon (company) / Wikipedia
- Ryan Specialty: Pierce, C.C. (Charles C.), 1861-1946 / Wikimedia Commons (Public domain)
- BRP Group / BRP Onvia: Bing Images / thenaminggroup.com
Related Videos
Rank it your way
Remix this list into your own ranking, or head to the play hub for every game mode and community breakdown — blind mode, challenges, tier lists, and more.
You Might Also Like

Top 10 US Reinsurance Companies by Net Premium
top reinsurance companies by net premium

Top 10 US Life Insurance Companies by Premium Revenue
top life insurance companies by premium revenue

Top 10 US Investment Banks by Net Revenue (2026 Ranking & Comparison)
largest US investment banks by revenue

Top 10 Cryptocurrencies by Market Cap — March 16, 2026 Snapshot
#1 Bitcoin (BTC) · #2 Ethereum (ETH) · #3 Tether (USDT)

Top 10 CoinGecko — Top Cryptocurrencies — April 27, 2026
#1 Bitcoin (BTC) · #2 Ethereum (ETH) · #3 Tether (USDT)

Top 10 CoinGecko — Top Cryptocurrencies — March 20, 2026
#1 Bitcoin (BTC) · #2 Ethereum (ETH) · #3 Tether (USDT)